Wednesday, February 25, 2009

Market Update: 2 23 09 _ Consumers aren't confident


Is there any good news?

A friend of mine called this morning and wanted some good news. I didn’t have any handy so I told him I’d have to get back to him. As I drove to work I thought about the issue the whole way…I really gave it some thought and it was difficult to find anything in the realm of business that I could spin as good news. As our economy shifts from a capitalistic structure where men and women used to accept risk in pursuit of reward to one where people get rewarded no matter how the risk pans out we’ve got some real problems. The government is now subsidizing bad behavior and punishing good behavior on a grand scale. Have no fear if you spent more than you earned…we’ll just tax those that saved more than they spent and it’ll all work out OK on average. From a monetary standpoint we’ll make everyone equal...they won’t all be happy but they’ll be equal. If I went home tonight and gave my daughter her allowance money even though she had messed up her room and forgot to set the table, and I took the money out of my sons piggy bank to do it, my wife would think I had started smoking crack. It makes no sense but it appears that many politicians are determined to do just this. So where is the good news that my friend was looking for?

Wisdom from the mouths of babes

My 9 year old son has been begging me to buy him a iPod Touch. For those that are unfamiliar with this gear it is essentially an iPhone without the phone feature. It gives you all of the multi-media functions…pictures, movies, music, web surfing etc. It costs in the neighborhood of $250. I imagine that all of the toys I owned when I was 9 years old wouldn’t add up to $250 combined so there’s not a lot of hope for the kid that I’m just going to drop that kind of coin on a toy. I dismissed the idea on the spot and I moved on…he didn’t.

Last night my little capitalist goes to his momma with a plan. He has a written proposal where he has outlined jobs that he can do to earn money, things he can quit doing to save money, and he has a timeline for making the purchase on his own with his current savings plus the capital he thinks he can raise under his plan. I couldn’t be any prouder of the kid. At NO TIME did he suggest that we tax Jim and Fay our next door neighbors to raise the money necessary to buy him an iPod. If a second grader can get this concept I don’t understand how so many people in America can miss it. The concept is simple…he can’t get what he wants by doing nothing so he comes up with a plan to WORK for it. He’s going to invest his time, his effort, and his emotions in this project…putting those items at risk in the pursuit of the reward that he wants. So that’s the good news…American kids still “get it”. The American Dream isn’t dead, it’s just that many of those that are supposed to be protecting it aren’t doing their jobs.

So with the good news out of the way…let’s look at the rest of the news from today.

Testify

First let’s look at some of Bernanke’s testimony from this morning. Those of you that have been getting my market updates for the last year will get very few surprises from today’s testimony. Last year I began writing that the government is fighting to avoid a Depression and I wrote a fair amount on Bernankes views on the subject. In Bernanke’s view, confidence in the financial system and maintaining access to credit for consumers and small businesses are paramount to recovery. Bernanke’s writings on the great depression state that the lack of these two factors caused what would have been the recession of 1933 to become the Great Depression. He is adamant that those two factors must be addressed and we are seeing strong action by the government to those ends. Large financial institutions are being given all of the help that they need to stay solvent. The government will not tolerate a crisis of confidence in these institutions. Despite the near hysteria in the media regarding nationalization of the banking system there is no talk from the current administration or from the Fed that this is in their plans. Nor is there any reason to believe that if they DID nationalize a bank that they would allow that bank to default on a bond. Allowing a bank to default on a debt obligation would cause a tidal wave of problems that run counter to everything that the government is trying to accomplish. As recently as this week Alan Greenspan was saying that even if some banks were nationalized that the government would have to protect the senior debt holders.

Based on everything that the government has said and done to date it is difficult to envision a scenario where a bond holder of one of these big financials in the TARP program takes a hit.


How Confident are you?

Consumer Confidence posted an all time low reading this morning. This data series began in 1967. It has seen all of the highs and lows that this country has been through since that date and today’s report shows that consumers are the least confident they have been since this series started in the late 60’s. I highlighted a few of the low points from this series since 1967 and I pulled a few random facts from the headlines of each period to give you a feel for what accompanied each low point.


The Richmond Fed index was released today. This is the latest in a long string of abysmal manufacturing data. Like the Empire manufacturing report and the Philly Fed index that were released earlier this month, this is a diffusion index which means any positive number indicates expansion in manufacturing activity and a negative number indicates contraction. The survey expected a bad number…a really bad number…and the Richmond Fed index delivered. The expectation was for a -49 and the actual release was a -51. You can see that this release was easily the worst since Bloomberg began reporting it.

The Case Schiller Home price index continues to decline on a Year-over-Year basis. There really isn’t much to say here…housing was a bubble and it’s correcting. Where she stops nobody knows.

There is still a lot of big news to come this week. Tomorrow we see Home Sales, followed on Thursday by Initial and Continuing Jobless Claims as well as Durable Goods. If you have any questions on this material please let me know.


Thursday, February 5, 2009

Market Update: Jobless _ 2 5 09

Treasury yields are falling this morning as the market rallies on very poor Initial Jobless Claims data. Overall they are still higher than they were a month ago. It’s strange times when I can report that the short end of the curve is up significantly but that it still remains at an insignificant level. The 3-month bill was trading to yield 0.08% a month ago…it’s up 233% to offer 0.29% this morning. Not a tremendous amount of yield but certainly better than the negative yields at which it traded in late 2008.


Initial Jobless Claims were released this morning and they were far worse than even the very pessimistic Bloomberg Survey expected them to be. A quick note is in order on Initial Jobless Claims…this is a WEEKLY figure that tracks the number of NEW filings for jobless benefits. The Bloomberg Survey expected that 580,000 people would file for initial jobless benefits last week…in actuality 626,000 people walked in and filed. 626,000 people in a week. According to Bloomberg that is a 26 year high.

In the prior release the survey also fell short of reality as they expected 588,000 initial claims and we actually got 591,000. Since jobless claims surprised on the high side of an already terrible expectation in the prior week, it looks as though the survey thought things couldn’t get worse because they lowered their expectation for this week’s number. After being beaten on the high side the survey dropped the expectation from 588k to 580k…and then the market delivered this week’s 626k…beating the estimate by a much larger amount than it did on the prior release.

Here is a number that surprised everyone in this office…last MONTH 2.8 people filed for initial jobless benefits. That’s a lot of people on the street and there doesn’t appear to be a quick end to this process.


Below are two graphs to put the initial claims numbers in perspective. The first is a medium term graph showing the last 9 years of jobless claims. The second captures initial claims data stretching back to 1967.


A longer term look at Initial Claims shows that we are at 1980’s type levels of claims.


The graph of consumer credit below is a lagged series…the data is two months old when released. This index covers most short-term and intermediate-term credit extended to individual, excluding loans secured by real estate. The graph below shows how much the consumer began tightening up toward the end of 2008. The last data point on the graph below is from 11/30/08 and it’s among the largest drops in the history of the series. This isn’t entirely unexpected. As consumers begin realizing that times are going to get tougher, they save more, spend less, and clean up their balance sheet. This is a good news/bad news proposition for the economy. Americans with stronger balance sheets is a very good thing, but the process of getting to that point will involve a lot of friction. By definition the more the consumer saves the less he spends, and the consumer is 2/3’s of GDP. You don’t need as many people selling cars and TV’s if the consumer quits spending, so the economy sheds job.


Taking a look at the big picture we can use the Federal Reserve’s Total Consumer Credit Outstanding index that I’ve attached below. This index is also lagged by two months so the numbers do not reflect anything that has happened since 11/30/08. Total Consumer Credit Outstanding also shows signs of reduction. Some of this will happen as consumers clean up their balance sheet and some will happen as consumers go bankrupt.

The governments current plan is to get spending going again and to gets banks lending. They would love to see the line below keep moving up. But that begs the question…where does it stop? Eventually we’re going to have to pay back the trillions of dollars that are being spent to revive the economy. If the consumer is so saddled with personal debt when the payback period on the government debt begins, where will it leave us? How can the economy be expected to grow in the future if it’s burdened by tremendous amounts of debt and the higher taxes needed to pay it off?

The graph below shows that total consumer credit outstanding as of 11/30/08 was $2.57 Trillion. Even if you just do the minimum monthly payment the consumer is having to come up with a decent amount of cash every month to service that debt. Now throw on top of that consumer debt figure the additional debt that will be issued to fund the government spending over the next few years and you’ve got a very large obligation to deal with. Taxes will have to go up to fund the government spending, which will reduce after tax cash flow with which the consumer can pay back his personal debt or invest in prospects that would spur economic growth.

As it stands now the government wants to issue a few trillion dollars in debt, create a bunch of government jobs, and force the banks to make loans that will push total consumer credit higher at the same time. Conceptually I wonder what our prospects for growth will look like at the end of all of this. It would seem reasonable that once we get this apple-cart stabilized there will be so much debt to pay off that there won’t be much money left over to fund future economic growth. Could we be looking at years of GDP growth in the 0 to 1% range? As ugly as the current situation is, some of the answers under consideration look even worse.

If you have any questions on this material or if there is anything I can be doing for you just let me know.


Tuesday, February 3, 2009

Market update: Stimulus and bank closings_2 3 09


Recent activity


The headlines recently have largely ignored the economic data and bank closings and focused instead on the stimulus bill. The economic data continue to grind out disappointing numbers, although GDP was less negative than the survey expected, and there are a few encouraging signs amid the carnage. The stimulus bill is rightly taking center stage at the moment. There is a tremendous amount of taxpayer money being requested which on its own will force taxes to rise in the future and will serve as a drag on future growth. As this process moves further into the political arena it necessarily moves further away from the economic arena. I will attempt to keep all of my comments and analysis in the economic arena as:


A – I know how that world works, and;


B – my language will be better


One of the biggest concerns about the package is that there will be a lot of wasted expenditures. Depending on one’s view of the severity of our current economic problems you might view all of these expenditures as wasteful but that’s an argument for another day. Wasted expenditures are those that don’t address the problems at hand and will unnecessarily burden the taxpayer and the economy for years to come. At this point, those of us that actually pay taxes (and I’m confident that everyone on this distribution list falls into that category) are more concerned about the long term tax effects of the stimulus bill than those that are writing it…this makes perfect sense as it’s getting tough to find anyone in Washington that actually PAYS their taxes.


They took my job but left my bills


I’ve attached a graph below showing the long term trend in Personal Savings as a percentage of Disposable Income. In laymans terms this simply shows how much Americans save. The trend is pretty clear, since the late 1970’s Americans have been willing to operate with less of a cushion in terms of savings. As access to new and widespread forms of liquidity became available, from credit cards to home equity lines people spent more and saved less. This trend continued until very recently. This index actually went negative in August of 2005, an event we hadn’t seen since the Great Depression. The difference though is that during the Great Depression Americans depleted savings to survive the tough economic times…in August of 2005 Americans did it to buy stuff…generally stuff that depreciates in value.


So where are we now? Now we see this savings rates rising in a hurry. People are scared, and cash is king when people get scared. I think it’s a safe bet to say that at this point everyone in America knows of someone that has lost their job (or taken a pay cut to keep a job). You can’t go anywhere and not hear about someone getting laid off or fired. This conversation doesn’t go un-noticed by those that still have a job. They begin saving in case they lose their own job. It’s an unfortunate fact that when you lose your job you don’t lose your bills with it. You keep those you just have no way to pay them (especially if your savings rate has been close to zero). So people save. They build a cash cushion on which they can survive if the unthinkable happens. This is exactly how things should work…finally we are acting in a rational manner…it just took a trip close to a depression to make it happen.


The short term pain from this improvement in American savings is that consumers won’t be spending. Consumer spending accounts for roughly 2/3’s of GDP and if Americans are saving rather than spending then GDP can’t improve. The government at this point will increase it’s own spending to make up for the lack of consumer spending. This will clearly increase spending but the ironic part of this is that it will ultimately increase taxes which will depress consumer expenditures at some point in the future. This proves the old adage that there is no free lunch…but you CAN finance the lunch and pay for it a little at a time...with the minimum monthly payment.


In addition to traditional government spending programs the government is also pulling a lot of strings and re-writing a lot of rules to entice the consumer back into the game. They are making a Hurculean effort to reverse the savings trend. Despite the fact that saving is good, the government wants Americans to quit saving and start spending to get the economy out of the ditch. This is why you see such a hard push to get the refinance activity going. If every good borrower in the country get’s to refi to a 30 year 4.00% mortgage it will provide a lot of extra cash in the consumers pocket. This is cash the government expects will be spent, but at the moment it appears that the average American may be more inclined to save it.


Closing time, you don’t have to go home but you can’t stay here.


After a short break from closing banks, the FDIC got back to business this weekend by closing 3 institutions around the country.


Failed Banks:


Three financial institutions were closed over the weekend. Ocala National Bank in Ocala Florida ($235 million), MagnetBank in Salt Lake City ($300 million), and Suburban Federal Savings Bank in Crofton Maryland ($354 million). The reported asset sizes are as of 3Q 2008.


The most recent quote I’ve seen puts the FDIC’s troubled bank list around 170 banks. My contacts throughout the banking/regulatory/investment world seem to think the 170 number is far too low, and if I use history as a guide I tend to agree with them. To provide a bit of perspective consider the following quotes from the FDIC’s Sheila Bair:


- In 1989 at the peak of the S&L crisis the regulators had closed roughly 534 institutions


- In 1990 there were 1,500 banks on the FDIC’s Troubled Bank List


Given the complexity and scope of the problems we face today I would not be surprised to see the FDIC Troubled Bank list grow substantially from its current level of 170.

Will Mortgage refinance activity pick up?


There have been a LOT of different ideas considered in order to find a way to start the refi machine. I’ve written about many of them as they come up in the news. One of the most recent ideas is likely to hit the Senate floor during the debate over the stimulus bill this week:


Government insured and subsidized 30 year 4.00% mortgages. This plan would push banks to make these loans to qualified borrowers. Preliminary talk is that there would be some period of years on the front end of the mortgage during which performance is guaranteed by the government. Since mortgage rates are currently much higher than 4.00% the government will pay the difference…I say again…the government will pay the difference between the market rate and the 4.00% level. That is one option being considered. This is a great example of what we mean when we say don’t bet against the government…if they want it badly enough they will get it. Currently they want a refi wave and they have taken no options off the table. It is quite a plan to use taxpayer money to get homeowners an artificially low rate on their home…if they view this plan as workable I can’t rule anything out.


I’ve provided a link to the story where this was reported.


http://money.cnn.com/2009/02/01/news/economy/Senate_stimulus_housing/index.htm


If you have any questions on this material or if there is anything I can be doing for you just let me know.


Monday, January 26, 2009

Market Update 1 26 09 _ Regulators close the third bank of 2009


The third bank to be closed by the regulators this year is 1st Centennial Bank in Redlands California. I was looking at this bank Sunday after I saw the announcement and it looks like the problems in the loan portfolio snowballed very quickly. The annual report for 2007 stated that NPA’s plus loans 90 days delinquent were $15 Million on a loan portfolio of roughly $520 million. That number rose from $15 million to $111 million over the first 9 months of 2008. They essentially had 20% of the loan portfolio go bad by the end of the 3rd quarter 2008.

You can take a look at the map below and get a good feel for what’s going on in California right now. That market is like a minefield…you don’t know you’re in one until it’s too late and not everybody gets to come out alive.

The map below plots the percentage change in NPA’s for banks around the country on a county by county basis. The darker the red the higher the NPA’s. 1st Centennial had 5 branches, 4 of them were in geographic areas in which banks are experiencing high rates of NPA’s. I would not be surprised to see a lot more bank failures coming to us from the darker red regions on the map below.

If you have any questions on this material just let me know.


Friday, January 23, 2009

How much money can you waste and STILL get bailed out?

Allllrighty then. It’s Friday and unless someone calls in to buy a bond today we will have a short quiz. I need to start with a big thanks to a good friend of mine in Texas who pointed this story out to me yesterday.

What do the following list and the picture underneath it have in common?

The list:

a. Operating with an inadequate level of capital for the kind and quality of assets held;

b. Failing to provide adequate supervision and direction over the officers of the Bank;

c. Operating without an appropriate risk management program that establishes acceptable risk exposure and ensures appropriate policies and practices are in place;

d. Allowing the payment of excessive compensation, fees and benefits to its senior executive officers;

e. Operating with an excessive level of criticized assets;

f. Operating without effective underwriting standards and practices;

g. Operating without an effective loan documentation program;

h. Failing to provide for an effective system to identify problem assets and prevent deterioration;

i. Engaging in speculative investment practices and failing to prudently diversify its equities portfolio;

j. Operating without a system to monitor and evaluate earnings and ensure maintenance of adequate capital and reserves;

k. Operating with deficient earnings;

l. Operating without sufficient liquidity, in light of the asset and liability mix and overall financial condition of the Bank; and

m. Committing violations of law and regulation.


Answer: They BOTH are mentioned in the Cease and Desist order that the FDIC levied upon Boston’s OneUnited Bank before a US Congressman pulled some strings to get them a TARP capital injection.

What is wrong with this picture?

I’ve written about my concern over the direction of this bailout/stimulus package once the politicians get involved. I hold a dim view of the ability of politicians to use reason and sound economic principles to act wisely when spending our tax dollars…especially when they’ve got enough political cover to hide their tracks.

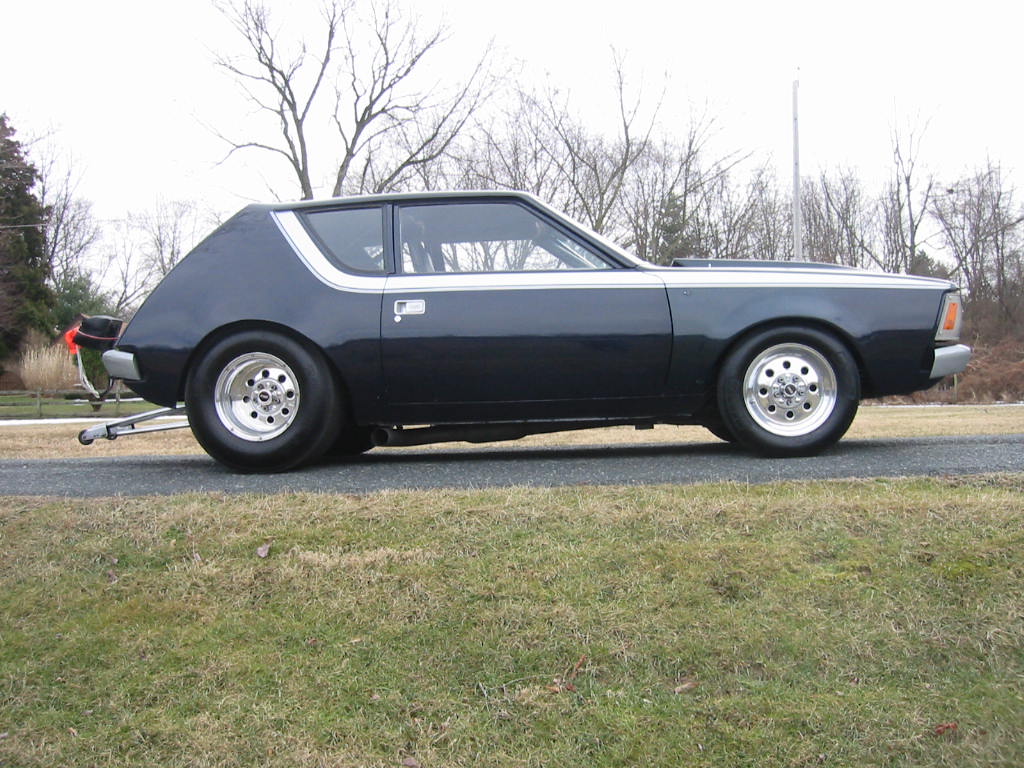
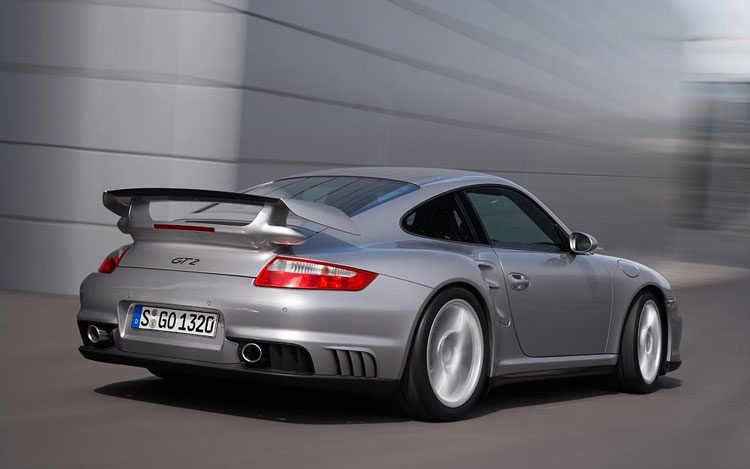
Among the many executive perks is a 2008 Porsche Cayenne. Pictured below is the Porsche Cayenne…SUV. It is the fastest SUV on the planet, but in my view (and if you own one or if you work for Porsche you might want to skip this next comment) it reminds me of the 1972 AMC Gremlin (see pic below the Cayenne for the considerably older and less expensive AMC Gremlin).

The Porsche Cayenne costs between $44,000 and $78,000 depending on options.


The AMC Gremlin costs roughly $3,200 (without the wheelie bar and drag chute).


This in my opinion is the most eggregious error in judgement to come out of this whole mess. If the board authorizes you to get a NEW PORSCHE I don’t see how you would EVER choose the Cayenne. It wouldn’t even make my Top 5 list…I would start with a GT2 and if anyone cried about the price I’d remind them that here at OneUnited we don’t let cost/benefit analysis or “legality” cloud our decision making process.


The GT2 is much, much faster than the Cayenne and it looks way better too (the Cayenne runs 0-60 in 7.5 seconds vs the GT2’s speed of 3.6). So I’d start with the GT2 and if they pitched a fit I might consider moving down to a 911 Twin Turbo.

Besides…who would you want to get a loan from…a guy driving an AMC Gremlin or a guy driving a GT2?

*As I was writing this George looked over my shoulder and pointed out that an additional benefit of the increased marginal speed of the GT2 is that it will allow you to better outrun the regulators.


Oceanfront Property

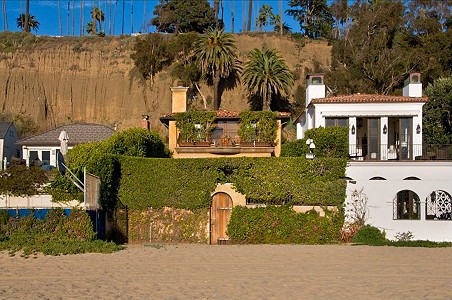
Now let’s get on to their beach house. It is being reported that the bank had a beach house in Santa Monica because they have several branches in Southern California and due to the amount of time they spend checking up on things they needed a place to stay.
The property is currently listed at $7.35 million.

Description of where OneUnited executives stay when on the road (from the real estate site that is selling it now):

Seller's Description:

On the Santa Monica Gold Coast, this ocean front estate is very private with a welcoming front courtyard & rear yard with swimmers pool. A gated Family Compound with three bedrooms and three and a half baths, plus a media room. Also a two bedroom Full Guest House. High ceilings, wood floors, pillared archways and venetian textured walls. French doors open to a romantic loggia, patio, pool and spa. Master suite with marble fireplace and a spacious terrace that enjoys a spectacular ocean view. Drift off to sleep with the waves hitting the sand.
Here is a link to the site that is listing the property. I’d suggest that if you have any interest in the property that you buy it right away because once everyone figures out you can get TARP money to bail you out of decisions like this there will undoubtedly be a bidding war: http://www.zillow.com/homedetails/703-Palisades-Beach-Rd-Santa-Monica-CA-90402/20486931_zpid/


Description of where I stay when on the road (from the Hampton Inn website):


  • Many of our locations near airports offer complimentary shuttle service to and from the airport for your convenience.

  • Our curved shower rods make your shower space even roomier.

  • Our alarm clock radios are not only super easy to set and use, but also include pre-programmed buttons to take you straight to your favorite kind of music on the radio.

  • Use our portable lap desk to work or read in comfort from anywhere in your room.

Now clearly in hindsight we can argue that spending $7.5 million on a house so you can efficiently run your west coast operations might seem excessive given that you weren’t efficiently running anything except your Porsche SUV. But…I wasn’t on the board and I must not know as much about this situation they do, nor as much as Congressman Barney Frank who actually wrote verbiage into the TARP bill to help this bank.

From the Wall Street journal article on this topic:

“Mr. Frank, by his own account, wrote into the TARP bill a provision specifically aimed at helping this particular home-state bank. And later, he acknowledges, he spoke to regulators urging that OneUnited be considered for a cash injection.”

I don’t know if it’s funny or sad that the taxpayers just shelled out $12 million to help this bank. They spent close to $8 million on a house and a car and ran a bank into the ground. I spend maybe 30 days a year on the road at an average per night of $115.00 and I use the cheapest car I can find from the airport rental counter (within reason of course, I draw the line at the Toyota Prius Hybrid and I won’t drive a mini-van), plus if I have time…breakfast is free at the Hampton. All in all, I’ll spend about $4,000 in travel expenses for the year…and I see a lot more banks than the executives from OneUnited do. I think I would be a better recipient of $12 million in TARP funds than OneUnited. On that note I’ll wrap this up…I need to call my senator and see if he can hook me up.

If you have any questions or if you have any suggestions on how I might spend my TARP money just let me know.

Thursday, January 22, 2009

FW: Market Update: 1 22 09 _ How much will the government spend?

The new administration says they are bringing hope and change. In the case of the financial bailout/stimulus/TARP plan I hope the change isn’t as big as the numbers I’m hearing from some new administration insiders. Over the last two days there have been a number of interviews with key personnel in and around the Obama administration that have contained clues as to the direction of the financial stimulus plan. People like former Fed Chairman Paul Volcker, Democratic Senator Chuck Schumer, and tax-evading NY Fed President and soon to be Treasury Secretary Geither (If a lowly bond-salesman or perhaps even a banker landed before congress and was getting grilled over not paying their taxes I doubt if a simple “sorry ‘bout that guys” would do them much good.)


Geithner’s comments on the stimulus plan:

“The ultimate costs of this crisis will be greater if we do not act with sufficient strength now,” Geithner said in testimony at today’s hearing. “In a crisis of this magnitude, the most prudent course is the most forceful course.”


From Volcker:


“Volcker says to get through the crisis, “several trillions of dollars” will need to be committed by various government programs. Volcker apparently spoke at Geithner’s Dartmouth commencement 25 years ago. “My memory is that the public address system closed down” after beginning the address, Volcker says. He says Geithner has “unique qualifications” from hands-on experience, understanding of financial markets and support of President Obama.”

Senator Chuck Schumer:

“Sen. Chuck Schumer said he spent some time calling around Wall Street this weekend, and what he heard was that if the government wants to clean out all the toxic assets from the financial system, it will cost some three to four trillion dollars. Which is to say, an order of magnitude larger than the second $350 billion in TARP money the Senate just approved.”


With these early quotes coming out it has the feel of the start of a very large string of expenditures.

One final quote is from Nouriel Roubini, professor of Economics at NY University, and a guy that has been incredibly right during this economic cycle:


Jan. 20 (Bloomberg) -- U.S. financial losses from the credit crisis may reach $3.6 trillion, suggesting the banking system is “effectively insolvent,” said New York University Professor Nouriel Roubini, who predicted last year’s economic crisis.

Economic Data

This morning’s economic releases point to continued problems in the housing market and increasing numbers of initial jobless claims.

Yesterday Bloomberg ran an article stating that the median price of a home in San Francisco last year was $557,000. The median price today is $330,000. It would appear that we are not done with the depreciation in some housing markets.


Housing Starts were expected to post 605,000 for the month of December, they actual number was 9% lower at 550,000.

Initial Jobless Claims were roughly 8.5% higher than the survey expected. 580,000 new people applied for unemployment benefits in December. The outlook on jobs in the first quarter appears to be less than great. Each day on Bloomberg I see headlines that show which companies are letting people go and in what numbers. Circuit City alone will put 34,000 people out of work as they complete their liquidation. Bank of America is reported to be cutting 35,000 jobs over three years. The list gets longer each day.


Below I’ve attached a graph of the Unemployment Rate, which is currently at 7.2%. Given the current state of affairs I’m not seeing much that would indicate that this rate will experience a significant departure from its current trajectory. The current Bloomberg survey on the Unemployment Rate shows an average expectation of 8.00% for 2009 with the high estimate being 9.00%.


The highest point on the Treasury curve this morning is 3.15%...at the 30 year mark. Under a year in Treasuries you’re looking at 40 basis points or less in yield…MUCH less at the 1-month and 3-month marks.


MBS spreads are volatile but trending toward much tighter as the government purchases of MBS product continue. This is all part of the master plan to induce a refi wave. Refi’s have increased dramatically over the last few weeks. I would expect refi’s to be volatile as well because there are still a number of roadblocks in the way of the government’s plans to get the refi boom going. First is the fact that many homes are currently worth less than the outstanding mortgage, secondly many of the borrowers that they would like to see refi won’t qualify. There are a number of initiatives that the government is exploring currently that will allow them to get around these issues…none of which are great from the perspective of banks or fans of the free market.


I’ve run the Refi Index to show activity going back to 2000. Much like a child that has been burned by a hot stove I look at the prepay spike in 2001 and 2002 with great caution and respect. During that time period there were a lot of people burned by purchasing high premium bonds. As the prepays ramped up and some bonds payed at CPR speeds north of 70 CPR we saw everything from low yields to negative yields…even on products that had never before had a reason to do so.

Over the last few years I’ve heard many people say that we couldn’t see that again especially in a credit crisis as nobody can get a loan so it’s OK go buy any sized premium you want. I disagreed with that assessment as it is very one-dimensional, ignores history, and completely rules out the possibility of government intervention in the markets. Over this cycle we’ve tried to minimize premiums whenever we could. At this point it is almost impossible to find an MBS anywhere near 100. There was a joke back in 2001 and 2002 that 102 is the new par on MBS. That joke was unpacked and used again last week…as soon as I heard it I was reminded of the refi wave.


What do we do?

So with the government actively trying to induce a refi wave, banks holding large amounts of MBS securities, and concern mounting over runaway inflation sometime in the next few years what is one to do?

Many banks would like to sell into the government buying spree to take gains but if you sell…what do you do with the money? Full Faith and Credit has been popular but the yields on a standalone basis are fairly unattractive.


Many banks have the ability to take advantage of the government in two directions. The first is that you sell your higher premium MBS into the flurry of government buying to take gains of 2 points or more. With the proceeds you can purchase 2 year Full Faith and Credit issues from the FDIC’s TLGP program at yields around 1.30%. The 2.00% gain on securities combined with the 1.30% annual yield on the Full Faith and Credit bullets gives you a 3.30% yield for the year, shortens your duration, and allows you to capture those gains before the refi wave erodes them.


For those banks that can take some credit risk there are even better yields available from the non Full Faith and Credit issues from the same companies that are issuing FDIC paper. These issues get indirect support from the issuers ability to refinance currently outstanding paper at full faith and credit levels. The FDIC insurance program runs through June 20, 2012 as currently written. Buying issues that mature before this window closes adds another level of comfort. Yield levels on maturities of less than 3 years range from 2.00% to north of 6.00% on these issues.


Using either of these reinvestment options provides you with a great opportunity to position yourself very well for rising rates a year or two from now.

Factors that may aggravate inflation

As much as the Fed would like to keep rates low there is real concern regarding rising rates from factors outside of their control. China surpassed Japan as the largest foreign holder of US Treasuries this year. China will have less money to spend on Treasuries first of all due to our recession…we’re simply not sending them as many US Dollars because we’re not buying as many of their exports. Secondly, China is dealing with a recession of their own and are going to have to deploy some of their excess cash on domestic programs…this also means less money to invest in US Treasuries. Thirdly a decline in the value of the dollar will translate into lower investment returns for foreign holders of US dollar denominated assets. Another concern is that foreign central banks at some point begin pricing in higher yield requirements based on expectations of higher inflation in the future.


So despite the Feds actions so far there are some plausible scenarios that could cause this yield curve to steepen significantly over the next two years. If that happens you don’t want to be the bank that stretched on maturity or sacrificed structure to chase yield.


If you have any questions on this material or if you would like to see swaps that involve selling MBS to take gains and redeploying into short Full Faith and Credit bonds just let me know.

Tuesday, January 6, 2009

2008 Review

2008: One for the record books

Every now and again in life you find yourself in the midst of a whirlwind, and by the time you get a chance to look up, things have changed so drastically that you wonder “what-on-earth-has happened?”  The first time I ever experienced this I was 18 years old.  I had enlisted in the Marine Corps and before I knew it I was in a big room on a small island off the South Carolina coast with 60 other guys and a bunch of very angry strangers throwing things, yelling at us, and presumably bent on our personal destruction.  As I took in all of the chaos going on around me I realized it was difficult to remember exactly how I got here…I knew there was a plane, a bus, a few beers and a signature involved, but so many big things had happened in the interim that I had some difficulty remembering the details. 

That scenario reminds me a bit of year-end 2008.  I see a lot of crazy things going on around me, everything seems to have changed…but where did all of this start?  More importantly…where will it stop?

The sheer volume of activity that 2008 has brought us is compelling me to write two year-end reviews; one review will be fairly short and entertaining, the other will be longer, more detailed , and hopefully just as entertaining.  With that in mind, if you don’t have the time or desire to get bogged down in the details just hit this first part.  The rest of you can read both parts.

If we had to sum up 2008 in just a few short words I can think of none that are more appropriate than “systemic risk”.

The short story of 2008

Suppose that on December 01, 2007 you got a concussion that put you in a coma for a year and you awoke on January 01, 2009.  Upon awakening you would be hard pressed to recognize this market.

Picture a banker that after a year, escapes this coma, squares himself away and gets in to the office to catch up on things.  The first thing he sees is a mountain of cash in Fed Funds Sold.  “How did we get all of this cash?” he yells to his assistant.  The assistant dutifully informs him that everything that could be called has been called or is about to be called.

“Whew…well at least we’re getting 4.25% on it” says the banker.

“no boss…the Fed cut rates.”

“So we’re getting 4.00%?” our banker inquires.

“no boss, they cut more than once.”

“We’ve got this much money in Fed Funds sold at 3.75% !?!?!?” the bankers exclaims.

“no boss, we’ve got that much money sold at zero percent.  The Fed cut 425 basis points since last December.”

“We can’t have that…let’s get this money into some 1-month and 3-month T-bills to get some yield until we get a game plan together.”

“boss…t-bills are trading at negative yields.”

“You know that we’ve got a random drug test policy at this bank right?  Do I need to randomly test you right now?  Because I thought I heard you tell me that Treasury bills are trading at negative yields…did you start smoking dope while I was in the hospital?”

“no boss…just telling you the facts.  T-bills are trading with negative yields…we’re better off at zero percent on Fed Funds sold.”

 In shock he declares “OK, I’d better call one of our approved brokers and get this money put to work.  Get our guys from Bear Stearns, Lehman, and Merrill on the phone and see what they can show us.  Right before my coma they showed me a 15 year 5.00% MBS at a discount to yield 5.08%...call him and see if there’s any left!”

His assistant now explains that those firms don’t exist anymore…and that the bond to which he is referring is now trading north of 103 to yield a 3.35%.

“Ha!  Good one…you almost had me on that joke.  Now get Bear on the horn.” 

Drawing a blank stare from his assistant it slowly dawns on our banker that this isn’t a joke...every firm on his approved list really is gone…bankrupt…history…sayonara. 

“At least we’ve still got the old independent street firms like Goldman and Morgan Stanley right?” he asks cautiously. 

“Those are now banks sir…and I might as well tell you that Fannie and Freddie are in conservatorship, money market funds are guaranteed, Wachovia is gone, WaMu is gone, Indymac is history, there now exist corporate bonds that carry the full faith and credit guaranty of the US Treasury, the government is actively injecting capital into banks around the country, GM and Chrysler are on the rocks (but the government is going to use money set aside for the financial bailout to help the automakers), the FDIC’s problem bank list is almost at 120 institutions, most of the world’s major economies are in recession, and the government is fighting to keep another great depression from happening, our board meeting is this Wednesday, the FDIC will be here on Monday…and when you get a chance you’ve got 12,000 e-mails to follow up on.”

After a few moments of stunned silence our man responds “thank goodness I put all my money with Bernie Madoff right before the accident…he always cranks out an 8 to 12 percent return.”

With that, the assistant walks away. 


Here is a whirlwind tour of 2008 for those that appreciate brevity:

Emergency 75 bps Rate cut by Fed in Jan, One week later Fed cuts another 50 bps

Volatility in stocks and bonds

Banks around the world eat $1 Trillion in credit write-downs and losses since start of credit crisis in ‘07

Fannie and Freddie suffer quarter after quarter of multi-billion dollar losses before being taken into conservatorship

More volatility, Feds take over a bunch of banks

JP Morgan buys Bear, B of A buys Countrywide, B of A buys Merrill, JP Morgan buys parts of WaMu

Citi buys Wachovia, Wells steals Wachovia, nobody buys Lehman, systemic risk runs amuck

More volatility, Libor out of control, money market run, money markets govt. guaranteed

Everyone on the planet throws trillions of dollars at Libor, Libor doesn’t budge

Banks fear lending, Governments fear banks not lending

Bailouts for everyone, Its official….US Recession, Most major economies slip into recession

Holiday retail numbers are poor, GM and Chrysler get government help, everyone else lines up for a handout, get in line folks everyone’s doin’ it.

Bernanke tells us we’re going to be in a low rate environment for quite some time.

That’s the short story.